
 body {
all: initial;
}
body * {
all: revert;
}
header, footer, nav, .sidebar, .widget-area, .menu, #comments, .post-navigation, .entry-meta {
display: none !important;
}
.site-content, .entry-content {
margin: 0 auto !important;
padding: 20px;
max-width: 800px;
width: 100%;
}
body {
font-family: Helvetica, Arial, sans-serif;
margin: 0 auto; /* Center the section horizontally */
padding: 0;
background-color: #f4f4f4;
color: #333;
}
nav {
background-color: #333;
color: #fff;
text-align: center;
padding: 10px;
}
nav ul {
list-style: none;
margin: 0;
padding: 0;
}
nav ul li {
display: inline-block;
margin-right: 10px;
}
nav ul li a {
color: #fff;
text-decoration: none;
padding: 5px 10px;
border-radius: 5px;
transition: background-color 0.3s;
}
nav ul li a:hover {
background-color: #555;
}
section {
padding: 25px;
max-width: 860px; /* Adjust the maximum width as needed */
margin: 0 auto; /* Center the section horizontally */
line-height: 1.5;
}
table {
width: 100%;
border-collapse: collapse;
margin-bottom: 20px;
}
table, th, td {
border: 1px solid #ddd;
}
th, td {
padding: 10px;
text-align: left;
}
th {
background-color: #007bff;
color: #fff;
}
tbody tr:nth-child(even) {
background-color: #f2f2f2;
}
ul {
list-style: none;
padding: 0;
margin: 0;
}
ul li {
padding: 5px 0;
}
.product-image {
width: 250px;
height: auto;
}
footer {
background-color: #333;
color: #fff;
text-align: center;
padding: 10px;
bottom: 0;
width: 100%;
}
The 5 Best Furniture Financing Options for 2026
Last updated: 2026-10-16
Walking into a showroom and falling in love with a velvet sofa is a feeling most of us know well. However, that immediate spark often hits a brick wall when the price tag comes into view. Financing lets you bring that comfort home today by spreading the cost over several months or even years.
Deferring large expenses helps manage modern household needs. It is especially helpful when moving into a new place or replacing a mattress or dining table. You shouldn’t have to wait for a savings account to catch up just to sleep on a decent bed.
Picking a lender involves more than just looking at a monthly payment. You have to dig into the fine print and interest rates. You also need to know if a provider requires a perfect credit score. A high interest rate can effectively double the cost of your furniture. A $1,000 sofa can quickly become a $2,000 expense by the time you make that final installment.
Look past the initial aesthetic appeal. You must evaluate the mathematical reality of your debt. This review looks at the top contenders for home furnishings debt. Whether you want a short-term promotion or a long-term plan, knowing your options is the first step toward responsible decorating.
- Furniture Row
- FastLendGo
- Jordan's
- Rent-A-Center
- CashUSA
How These Lenders Were Evaluated
Evaluating furniture financing requires looking beyond the furniture itself. We focused on how flexible the terms are and how easy the application process feels. A zero percent interest offer sounds like a dream. However, those plans usually come with strict credit requirements.
Many “no interest if paid in full” plans demand a high FICO score. Lenders want to see stable, verifiable income to ensure they aren’t taking on too much risk. We also looked at how quickly you can actually get the funds. Some lenders focus on those with established credit histories to offer the lowest APRs. Others cater to people needing a second chance after credit hiccups.
We weighed the speed of approval against the total cost of borrowing. This provides a clear picture for every budget. Our evaluation analyzed these specific metrics:
- Speed of Approval: How long from clicking “apply” to having credit ready at the register?
- Transparency: Does the lender clearly state all fees, or are there hidden origination fees or late penalties?
- Flexibility: Can you pay the loan off early without penalties? This is vital if you plan to make extra payments to save on interest.
- Minimum Requirements: Is there a hard minimum credit score or a pathway for those with limited history?
| Lender | Max Loan Amount | Interest Rate Options | Credit Requirements |
|---|---|---|---|
| Furniture Row | see site | 0% APR available | Subject to approval |
| FastLendGo | $5,000 | see site | Bad, Fair, and Good |
| Jordan’s | see site | 0% APR for 24 months | Subject to approval |
| Rent-A-Center | see site | Rent-to-own | No credit needed |
| CashUSA | $10,000 | see site | see site |
Top Furniture Financing Rankings
1. Furniture Row
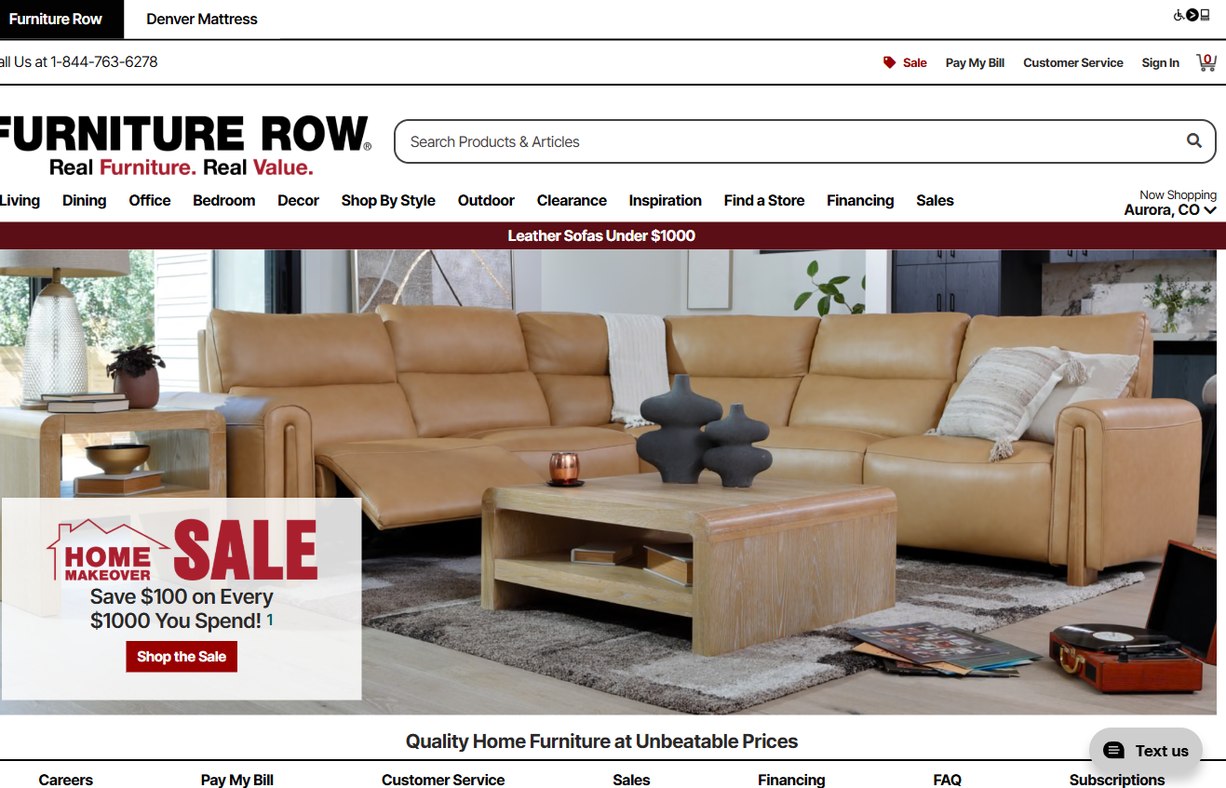
Furniture Row is a strong choice for those combining high-quality goods with specialized financial tools. They partner with various institutions to offer promotional terms. This variety helps shoppers find a plan that fits their specific lifestyle and budget. They offer a spectrum of options rather than a one-size-fits-all approach.
The availability of 0% interest financing is a major draw. For those who qualify, this avoids the heavy weight of interest. Imagine buying a $3,000 sectional sofa. With 0% interest over 12 months, you pay $250 per month. If you were forced into a standard 18% APR loan, that same sofa could cost you nearly $3,500.
This makes premium items feel much more attainable for the average household. Just make sure you can manage the monthly cash flow. It is a great way to get high-end items without a massive upfront hit to your bank account.
Pros:
- Special 0% interest financing available.
- Large selection of living, dining, and bedroom furniture.
- Options for both in-store and online shopping.
Cons:
- Requires qualifying for specific promotional terms.
- Missing a single payment can often result in “retroactive interest,” where you are charged interest from the original purchase date.
2. FastLendGo
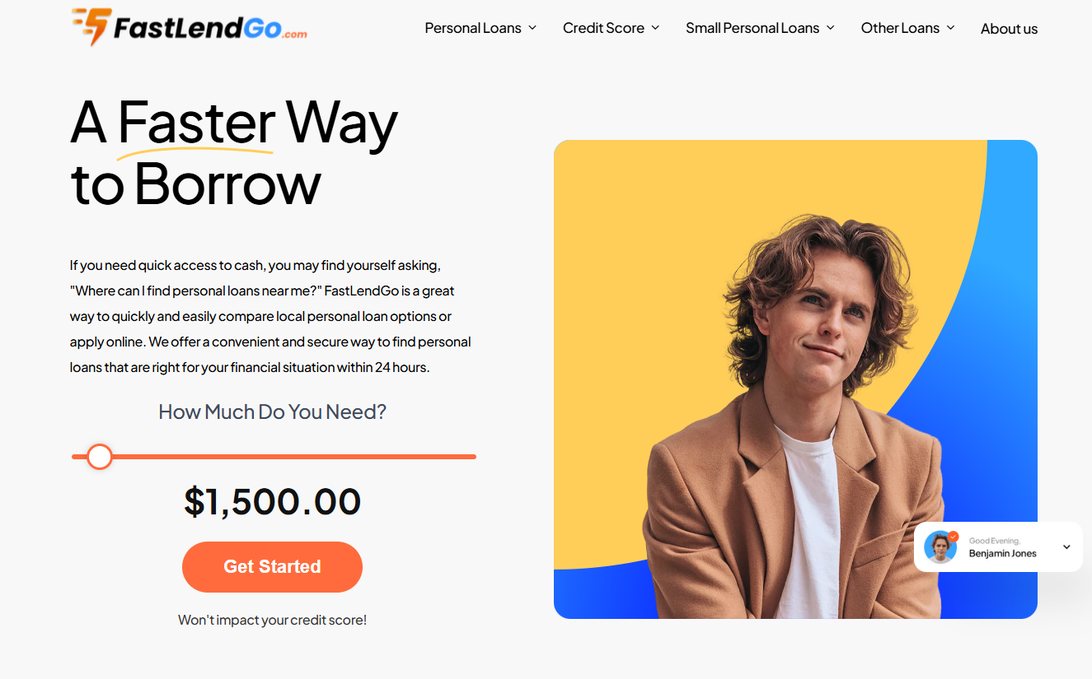
FastLendGo works well for anyone needing quick access to cash for various needs. While they handle more than just furniture, their personal loan structures are ideal for furnishing an entire apartment. Unlike store-specific credit, a personal loan from FastLendGo gives you total freedom. You can shop at multiple stores to maximize value.
They are particularly useful if your credit score isn’t exactly where you want it to be. By offering solutions for bad, fair, and good credit, they open doors that many traditional banks slam shut. This is a streamlined way to compare options without the headache of visiting multiple branches. It is a digital-first approach for a fast-moving world.
This is helpful if you need to furnish a rental property on a tight deadline. You get the cash in a lump sum and can shop wherever you please. It removes the restriction of being tied to a single retailer’s inventory.
Pros:
- Covers a wide range of credit scores.
- Provides loans from $500 up to $5,000.
- Fast online application process.
Cons:
- Primarily focused on personal loans rather than direct store credit.
- Terms may be shorter than long-term furniture-specific installments.
3. Jordan’s
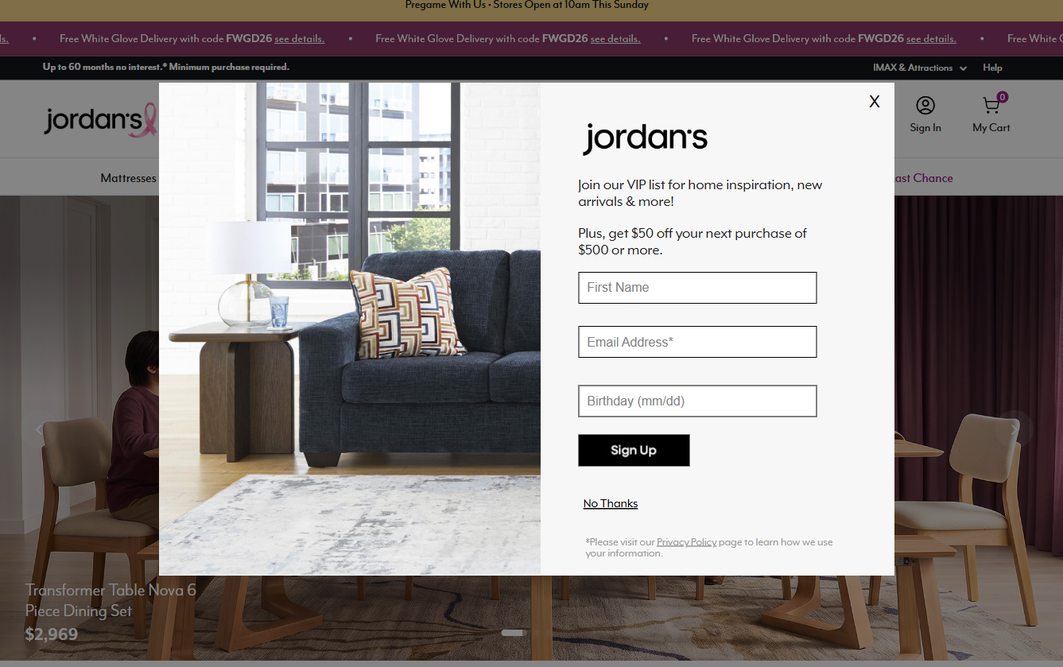
Jordan’s Furniture is a major player known for an impressive showroom experience. They offer sophisticated financing that makes high-end purchases feel manageable. Their promotions often include perks like free white glove delivery. This adds massive value to a large purchase by saving you labor and stress.
White glove delivery includes bringing items inside, assembling them, and removing all the packaging. When paired with high-quality goods, the financing becomes even more attractive. The 24-month 0% APR option is a standout feature for many buyers. It allows you to upgrade your bedroom or living room without the immediate sting of a massive bill.
It is a strategic choice for those with a steady income who prefer to preserve cash for rent or emergency savings. This “interest-free” window acts as a short-term loan. It lets your money work elsewhere while you enjoy your new home comforts.
Pros:
- Promotional 0% APR for 24 months.
- White glove delivery options available.
- Wide variety of home categories including gaming and outdoor.
Cons:
- Promotional rates are subject to credit approval.
- High-end inventory can lead to high total debt if not carefully managed.
4. Rent-A-Center
Rent-A-Center is the go-to option for those who want to avoid the traditional credit system entirely. Their rent-to-own model is built on flexibility. You can get the gear you need today without the immediate pressure of a long-term commitment or a formal credit check. This is essentially a lease-to-own agreement.
You pay for the use of the item, with the option to own it after a set number of payments. This is a lifeline for individuals in transitional phases of life. Students or people moving for seasonal work often find this model helpful. You can start with a small down payment and upgrade as your needs evolve.
For instance, you might start with a basic coffee table. After a few months of successful payments, you could swap it for a larger entertainment center. It provides a level of freedom that standard installment loans simply do not offer. You aren’t locked into one piece of furniture forever.
Pros:
- No credit needed to get started.
- High flexibility to upgrade or change plans.
- Low entry cost to start renting.
Cons:
- Rent-to-own models can be more expensive in the long run.
- If you do not complete the full term, you do not own the items and have essentially paid for “renting” without equity.
5. CashUSA
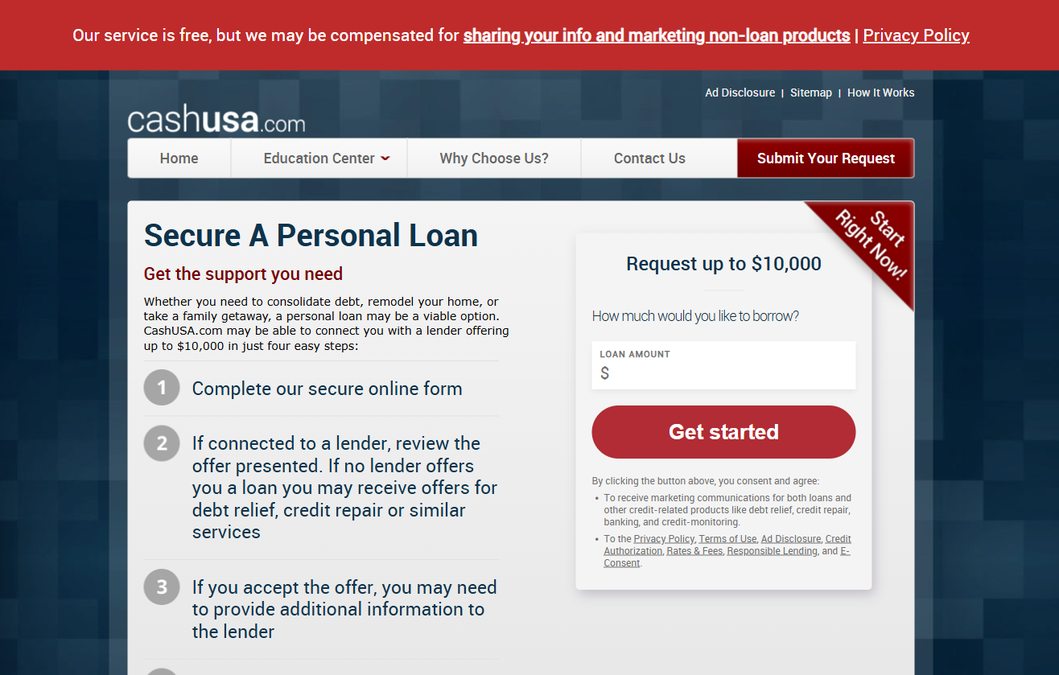
CashUSA operates as a digital connector. They help users find personal loans that meet specific criteria. If you need up to $10,000 to remodel a room, this service can point you toward a lender. It is a modern, efficient way to shop for credit. It works much like a comparison engine for your finances.
The process is designed to be simple. It typically involves just four steps: application, comparison, selection, and funding. While they may connect you to debt relief if a loan isn’t found, their primary goal is facilitating connections. This is ideal for the tech-savvy consumer who wants to see multiple options on a single screen.
You can skip the hours spent on the phone with different banks. Instead, you get a streamlined online experience. It saves time when you are looking to make significant household changes quickly.
Pros:
- Potential for loans up to $10,000.
- Fast connection to lenders.
- Simple, streamlined online application.
Cons:
- May provide marketing offers instead of loans if not matched.
Essential Questions to Ask Before Signing
Before you settle on a financing plan, perform a “stress test” on your budget. Many consumers fall into the trap of looking only at the monthly payment. A $50 monthly payment sounds incredibly manageable. However, if that payment lasts for 60 months, you are paying for that item for five years.
If the interest rate is high, you might end up paying for the item twice. Use this checklist when talking to a salesperson or a loan officer. It will help you avoid expensive surprises later on:
- “What is the total cost of the item including all interest and fees?” This is the most important number in the transaction.
- “Is there a penalty for early repayment?” If you get a bonus and want to pay off your sofa in month six, you should be allowed to do so without a penalty.
- “What happens if I am one day late on a payment?” Some contracts have strict “default” clauses where you lose all your 0% interest benefits and are charged backdated interest immediately.
- “Are there any origination fees or service charges?” Some lenders add a $100 “processing fee” upfront that isn’t included in the advertised monthly payment.
How to Choose the Right Plan
Before signing your name, look closely at the total cost of ownership. A low monthly payment can be deceptive if it is stretched over a decade. Always ask, “What is the total amount I will have paid by the end of this term?” This simple math reveals the true cost of the “deal.”
Avoid the trap of taking on more debt than your monthly budget allows. It is easy to get swept up in the excitement of a new dining set. However, financial stability is the foundation of a happy home. If you choose a rent-to-own option, remember you are paying for flexibility, not necessarily the lowest price.
Rent-to-own is a service for convenience. Personal loans and store credit are tools for ownership and building equity. Always check the interest requirements. If you qualify for a 0% APR deal, ensure you understand the penalties for a single late payment. One missed deadline can trigger a massive interest spike.
Stay organized and stay diligent. Use a calendar to track your payment dates. Consider setting up autopay so you never miss a beat. By being proactive, you can enjoy your beautiful new furniture without the lingering stress of debt.
{“@context”:”https://schema.org/”,”@type”:”Product”,”name”:”Furniture financing”,”description”:”Furniture financing — dosage, prices and buying information.”,”offers”:{“@type”:”Offer”,”priceCurrency”:”USD”,”price”:”4.57″,”availability”:”https://schema.org/InStock”},”aggregateRating”:{“@type”:”AggregateRating”,”ratingValue”:”4.9″,”reviewCount”:”476″,”bestRating”:”5″,”worstRating”:”1″},”brand”:{“@type”:”Brand”,”name”:”Furniture financing”}}原文链接:https://relive.xintheme.cn/fenlei-a/9215.html