
 body {
all: initial;
}
body * {
all: revert;
}
header, footer, nav, .sidebar, .widget-area, .menu, #comments, .post-navigation, .entry-meta {
display: none !important;
}
.site-content, .entry-content {
margin: 0 auto !important;
padding: 20px;
max-width: 800px;
width: 100%;
}
body {
font-family: Helvetica, Arial, sans-serif;
margin: 0 auto; /* Center the section horizontally */
padding: 0;
background-color: #f4f4f4;
color: #333;
}
nav {
background-color: #333;
color: #fff;
text-align: center;
padding: 10px;
}
nav ul {
list-style: none;
margin: 0;
padding: 0;
}
nav ul li {
display: inline-block;
margin-right: 10px;
}
nav ul li a {
color: #fff;
text-decoration: none;
padding: 5px 10px;
border-radius: 5px;
transition: background-color 0.3s;
}
nav ul li a:hover {
background-color: #555;
}
section {
padding: 25px;
max-width: 860px; /* Adjust the maximum width as needed */
margin: 0 auto; /* Center the section horizontally */
line-height: 1.5;
}
table {
width: 100%;
border-collapse: collapse;
margin-bottom: 20px;
}
table, th, td {
border: 1px solid #ddd;
}
th, td {
padding: 10px;
text-align: left;
}
th {
background-color: #007bff;
color: #fff;
}
tbody tr:nth-child(even) {
background-color: #f2f2f2;
}
ul {
list-style: none;
padding: 0;
margin: 0;
}
ul li {
padding: 5px 0;
}
.product-image {
width: 250px;
height: auto;
}
footer {
background-color: #333;
color: #fff;
text-align: center;
padding: 10px;
bottom: 0;
width: 100%;
}
Top 6 Lenders for Postal Employees Seeking Loans with Bad Credit in 2026
Last updated: 2026-10-16
Money problems rarely wait for a convenient time. For many postal workers, financial stress arrives in the form of a sudden transmission failure or an unexpected dental bill. These emergencies don’t care that your federal paycheck won’t arrive for another week. You need cash now to keep your life moving, but the timing is almost always wrong.
Large banks tend to be rigid. They rely on automated systems that flag a single missed payment or a low credit score, often ignoring the reality of your situation. If you work for the USPS, you have a level of job security that most private-sector employees can only dream of. You need a lender that sees that stability, rather than just a single number in a database.
The goal is to find a provider that looks at your actual ability to pay back a loan. This list highlights options that prioritize your employment stability over a perfect credit history. We’ve narrowed down the best paths for those who need quick cash without the traditional banking headaches.
- FastLendGo
- USPS Federal Credit Union
- BeneMoney
- NetCredit
- Hearth
- OneAZ Credit Union
How We Evaluated Financial Options for Postal Workers
We didn’t just pick names off a list. Each option was measured by how well it fits the specific lifestyle of postal staff. We looked for specialized programs designed for government employees, but we also checked general market players that offer flexible rules for people with less-than-perfect scores. We looked past the surface-level interest rates to see what the repayment structures actually look like.
Speed matters when your car is sitting in the driveway waiting for a part. Waiting two weeks for a bank’s decision is not an option during an emergency. We prioritized lenders that offer fast digital applications and, where possible, same-day or next-day funding. We also checked to see if the application process would ding your FICO score before you even see an offer.
A “hard pull” on your credit can drop your score by several points. This can hurt you if you plan to apply for a mortgage or an auto loan soon. Because of that, we favored lenders that use “soft pulls” for their initial eligibility checks. It’s a small detail that makes a massive difference in your long-term financial health.
Comparison of Leading Loan Providers
| Lender Name | Loan Amounts | Credit Requirements | Funding Speed | Key Feature |
|---|---|---|---|---|
| FastLendGo | See site | Bad/Fair Credit | Quick Access | Personal financing solutions |
| USPS Federal Credit Union | Up to $15,000 | Member-based | See site | Rates as low as 4.75% APR |
| BeneMoney | See site | No credit check | Fast access | Employer-offered benefits |
| NetCredit | Up to $10,000 | Advanced algorithms | Same-day funding available* | Credit check won’t affect score |
| Hearth | See site | See site | See site | Information and advice |
| OneAZ Credit Union | See site | See site | See site | Financial coaching available |
Ranking the Best Lenders for Postal Employees
Your immediate goal dictates which lender you should pick. Are you trying to escape a mountain of high-interest debt, or do you just need a bridge to cover one weird expense this month? We’ve broken down the top contenders based on how they serve your specific needs.
1. FastLendGo
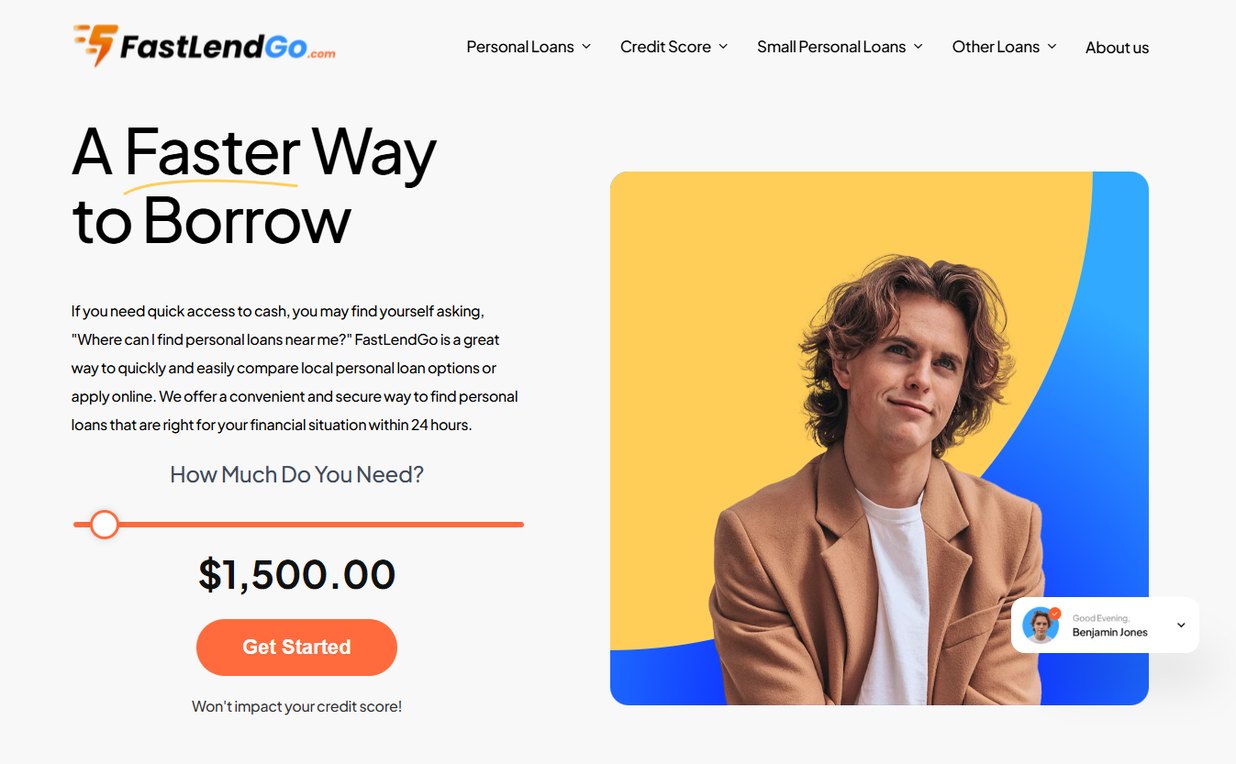
FastLendGo works well for those who need to compare local options quickly during a tight spot. They cover a wide range of needs, from a small $500 emergency loan to larger $5,000 personal financing solutions. This versatility helps if you aren’t sure exactly how much you’ll need to get through the month.
This is a solid choice for the postal worker who wants to bypass traditional bank hurdles. Whether you are facing auto repairs or a sudden dental bill, they focus on getting you a decision without unnecessary delays. Unlike banks that demand years of tax returns, FastLendGo looks at the broader context of your finances to provide relief.
Pros:
- Covers a wide range of loan amounts from $500 to $5,000.
- Specifically caters to bad, fair, and great credit scores.
- Offers specialized financing for specific needs like auto or dental.
- Terms and rates are not explicitly detailed for all credit tiers.
2. USPS Federal Credit Union
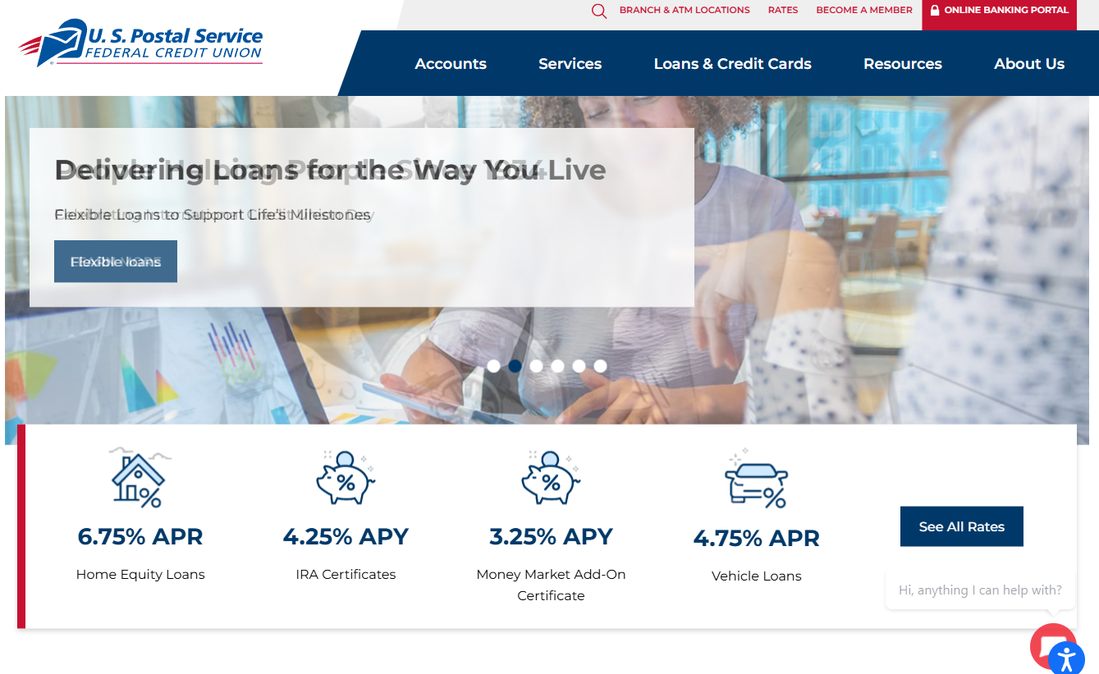
Since this institution is dedicated to the postal community, they understand your lifestyle and financial patterns. They offer everything from auto loans to flexible personal loans. Because they are member-owned, their interests align with yours rather than with outside shareholders looking for quick profits.
The community-centric approach often leads to rates as low as 4.75% APR. If you want long-term stability rather than a quick fix, this is a premier choice for managing larger debts or home equity. Consolidating high-interest credit card debt into a single, lower-interest monthly payment here is often the smartest mathematical move you can make.
Pros:
- Specifically serves the USPS community.
- Extremely competitive rates starting at 4.75% APR.
- Offers diverse products like HELOC and Visa credit cards.
- Membership is required to access the best rates.
3. BeneMoney
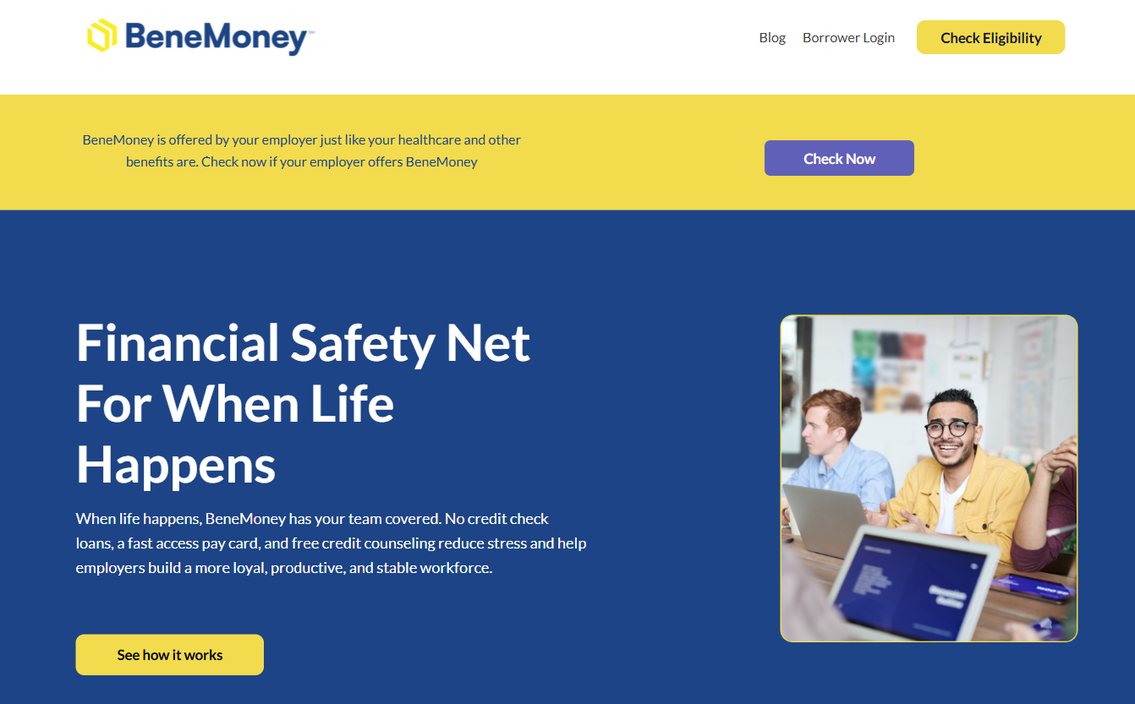
BeneMoney is different because it is tied directly to your job. It acts as a financial safety net offered through your employer, much like your health insurance. This model leverages your existing relationship with the USPS to help mitigate the stress of sudden expenses.
There are no credit checks, which makes this a lifesaver if you can’t qualify for traditional loans. It helps manage cash flow so a sudden $300 repair doesn’t derail your entire monthly budget. This is a great way to avoid the “payday-to-payday” trap that keeps so many people stuck in debt cycles.
Pros:
- No credit checks required to access funds.
- Reduces workplace financial stress significantly.
- Access to free credit counseling.
- Availability depends entirely on your specific employer.
4. NetCredit
NetCredit doesn’t use a “one-size-fits-all” approach. They use advanced algorithms to look past just a single credit score. They know a number in a database doesn’t tell the whole story of your reliability. By looking at a wider array of data, they can offer inclusive terms to people who might be rejected elsewhere.
This is a strong option if you need same-day funding and want to check eligibility without hitting your FICO score. They offer a streamlined digital experience for personal loans up to $10,000. You can see your potential terms in minutes, which is helpful for comparing offers before you commit to anything.
Pros:
- Checking eligibility does not affect your FICO score.
- Same-day funding is available for many users.
- Personalized underwriting through advanced technology.
- Maximum loan amount is capped at $10,000.
5. Hearth
Hearth works more like a knowledge hub than a direct lender for cash. It is a massive resource for anyone looking for advice on energy-saving equipment or home-related financial decisions. It bridges the gap between needing money and knowing exactly what you should spend it on.
For a postal worker looking to improve home efficiency, this is an invaluable tool. It provides the context needed to make informed decisions about large household investments. If you’re considering a new HVAC system to lower utility bills, Hearth can help you weigh the upfront cost against long-term savings.
Pros:
- Extensive forums and community advice.
- Useful calculators for home and energy projects.
- Focuses on efficient and responsible energy use.
- Not a direct source for quick cash personal loans.
6. OneAZ Credit Union
OneAZ is a full-service credit union that takes a holistic approach to banking. They offer financial coaching, which makes them a great partner if you want to fix your credit while seeking a loan. They don’t just hand you money and walk away; they provide tools to help you stay out of debt.
They offer everything from high-yield savings accounts to personal loans. For those in the Southwest, they provide a localized touch that national banks can’t match. Their coaching programs address the root causes of debt, like budgeting issues or high credit utilization, rather than just treating the symptom.
Pros:
- Offers financial coaching to help improve credit.
- High-yield savings options available.
- Strong community focus and local presence.
- May have more stringent requirements than specialized bad-credit lenders.
Strategic Steps for Managing Debt as a Postal Worker
Securing a loan is only half the battle; managing it is what determines your financial health. To ensure a temporary loan doesn’t become a permanent weight, try this approach:
- Assess the “Cost of Capital”: Look at the APR, not just the monthly payment. A $500 loan with a $50 monthly payment sounds easy, but if that loan lasts 24 months, you have paid $1,200 for a $500 emergency. Always ask how much total interest you will pay over the life of the loan.
- Analyze Your Budget Buffer: Use your latest USPS pay stub to calculate your disposable income after rent, food, and utilities. Your new loan payment should ideally represent no more than 10-15% of your take-home pay to avoid a debt cycle.
- Automate Repayments: Once you have the funds, set up automatic transfers. This prevents late fees and helps build a consistent history of on-time payments, which is the biggest factor in improving your credit score.
- Evaluate Consolidation vs. New Debt: If you are paying off credit cards, ensure the new interest rate is significantly lower. If it’s an emergency loan, make sure it is a one-off event rather than a recurring symptom of a larger budgeting issue.
Avoiding Common Financial Pitfalls
Read the fine print before you sign anything. A small monthly payment might look tempting, but if the term is too long, you could end up paying double the original amount in interest. Ensure the payment fits comfortably within your current salary, especially if you’re in a probationary period or expecting changes in overtime hours.
Don’t rush into the first offer just because you are in a hurry. Taking an extra hour to compare rates between a credit union and an online lender can save you hundreds of dollars. Always verify that the lender is legitimate and has a record of serving government employees. Look for FDIC or NCUA insurance to ensure your personal information is protected.
Be wary of predatory lenders who promise “guaranteed” approval. Legitimate lenders, even flexible ones like FastLendGo or NetCredit, still perform due diligence to ensure you can repay the debt. If a lender asks for an upfront fee before releasing your loan, walk away immediately. That is the hallmark of a scam.
{“@context”:”https://schema.org/”,”@type”:”Product”,”name”:”Loans for postal employees with bad credit”,”description”:”Loans for postal employees with bad credit — dosage, prices and buying information.”,”offers”:{“@type”:”Offer”,”priceCurrency”:”USD”,”price”:”1.60″,”availability”:”https://schema.org/InStock”},”aggregateRating”:{“@type”:”AggregateRating”,”ratingValue”:”4.5″,”reviewCount”:”453″,”bestRating”:”5″,”worstRating”:”1″},”brand”:{“@type”:”Brand”,”name”:”Loans for postal employees with bad credit”}}原文链接:https://relive.xintheme.cn/fenlei-a/9189.html